Paysera is an international fintech group with 700 employees and 20 years of experience developing innovative financial solutions. Originally launched as an e-commerce payment platform, Paysera has evolved into a full-spectrum financial services provider. As the first licensed electronic money institution in Lithuania, it combines the reliability of banks with the flexibility of fintech. In 2024 the clients of Paysera Group performed more than 10.6M transfers for over EUR 12B euros in 20+ different currencies.
Filip Mutafis, shareholder and Executive Director of Paysera Bulgaria and Paysera Romania
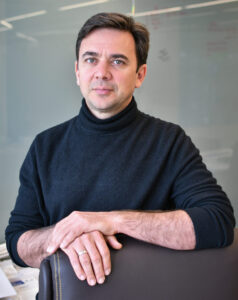 Filip, what is your vision about the future of payments in ecommerce?
Well, let me first tell you how I do not imagine it. I can`t imagine doing business in ten countries, for example, and having ten accounts with 10 banks in each country. This is where we are providing a game- changing solution. We are the only financial institution that, with one app, one login, one pricelist, one API, one account manager and one checkout, provides services across the Balkans. Banks tend to have territory restrictions to operate only in one country. Even the ones belonging to a group that has presence in different countries, their entities do not provide services in more countries. Opening one account does not make you a client in another country`s branch. This is the elephant in the room. Fintechs are not just about technology, digitalization or remote services through a mobile device. It is mostly about providing a cross-border experience in a unified Europe and, where possible, a unified world.
Are you saying technology and mobile apps are not enough?
Exactly. Try getting a Romanian IBAN from a Bulgarian bank or the other way around. Now imagine this at the EU level. However, e-commerce merchants need exactly that. And, of course, it`s not only e-commerce merchants, it`s everybody.
Here in the Balkans, card and cash on delivery dominate payments. Do you think this is going to change?
For the last five years, Europe has been pushing Open Banking as an alternative. At Paysera we have invested heavily to integrate with most banks in the region but the penetration level of the service is very low, unlike Lithuania or some Nordic countries where it is already the dominant payment method. Now, with the wide adoption of instant payments like Blink and SEPA Instant, I believe the game will change rapidly here as well.
What are the advantages for merchants? Why should they adopt Open Banking?
Open Banking technology enables account-to account transactions, so for merchants, this means receiving payments that are much safer and at a lower cost. Another benefit is that there are no chargebacks which can be a serious challenge in some industries. As for the end client, not all customers feel comfortable with the possibility of being charged by anybody who knows a 16-digit code, an expiry date and CVV.
You do, however, provide card payments as well?
Yes, of course. Our payment processor, Paysera Checkout, is mainly used to process card payments, and we have invested in the now mandatory 3D Secure, as well as Google Pay and Apple Pay, card tokenization and all the other features that make card payments more secure.
Your latest product is the free-of-charge Paysera Business Account which offers 30 free monthly transfers and an IBAN in EUR, BGN and RON. So, it looks a killer offer, but it doesn`t seem to have a spectacular adoption. Why do you think that is?
Indeed, we are onboarding more than 200 companies per month in Bulgaria alone, but they could be much more of course. The competition has intensified from all sides. Banks have invested heavily in technology, especially during Covid period, and are now releasing upgraded apps and products supported by huge advertising and promotions. They often provide payments products, linked to credit products, where we are defenseless. For example, if you need a loan, you definitely need to get a payment account linked to a monthly fee and other payment related benefits like a certain amount of free transfers.
Other fintech companies like Revolut and Wise have raised billions and are spending hundreds of millions on marketing and affiliate programs. Smaller local fintech start-ups are funded aggressively by accelerators and venture capital funds. In their struggle for growth, they are providing a plethora of free services, ignoring cost. They also intensively hire developers at above-market rates.
Still, the Paysera Business Account is an excellent option for trustworthy digital banking and provides excellent opportunities for companies doing cross-border business, especially after being accepted in the Schengen zone, along with Romania, and the boost of trade and connections between us. For countries like Kosovo, Albania and Northern Macedonia, the closer they get to joining the EU, the more business opportunities will increase with them as well.
Can companies from countries where Paysera is not present still open a Paysera account, for example, companies from Greece or Hungary?
Yes, of course. After they successfully complete the KYC procedure, they can take advantage of our services as well. They may not get customer support or a user interface in their native language, but we support 17 other languages.
We are using Paysera Tickets platform for this event. What is the role of this feature in the entire Paysera ecosystem?
The vision of Paysera it to become a Super-App -an app for apps, an app for financial apps. Paysera Tickets is just one of them. We have other live apps such as InRento and Heavy Finance for crowdfunding and we envision many more: for insurance, stock trading and others. Our feature for gold trading will also be improved into an app-within-the-app.
What about crypto?
Crypto is based on an advanced distributed ledger that provides many benefits. Unfortunately, crypto is mostly used for scams, fraud, hiding legit assets, and evading taxation. This is why we avoid crypto and we have a strong policy against it at least until it becomes much safer.