Cash on delivery in Central and Eastern Europe typically consumes 3 to 5 percent of transaction value when full operational costs are accounted for – often exceeding digital payment processing fees. Businesses that build systematic migration strategies toward online payment solutions and digital wallet adoption now will establish cost structures and competitive advantages that slower-moving operators cannot replicate. This guide covers the hidden costs of COD, the most effective digital alternatives, phased transition methods, trust-building strategies, and country-specific considerations across CEE markets.
Table of Contents
- Understanding Cash on Delivery in Central and Eastern Europe’s Evolving Payment Landscape
- The Hidden Costs of Maintaining Cash on Delivery Operations
- Online Payment Solutions as Alternatives to Cash on Delivery
- Digital Wallet Adoption Strategies for CEE Markets
- COD Reduction Methods: Phased Transition Approaches
- Building Customer Trust to Overcome COD Dependency
- Technology Infrastructure for Payment Processing Modernization
- Contactless Payment Growth and Its Role in COD Replacement
- Country-Specific Considerations Across CEE Markets
- Measuring Success in Cash on Delivery Reduction Initiatives
- Future Outlook: Payment Transformation in CEE Markets
- Frequently Asked Questions
Understanding Cash on Delivery in Central and Eastern Europe’s Evolving Payment Landscape
What makes cash on delivery so prevalent in CEE markets?
If you’re running an eCommerce operation in Central and Eastern Europe’s (CEE) eCommerce landscape, you already know that cash on delivery isn’t just a payment option – it’s a deeply embedded commercial habit. Customers across the region pay for goods at the moment of delivery rather than at checkout, and this single behavioral pattern shapes everything from your logistics workflows to your working capital position. What makes CEE so different from Western European markets isn’t just infrastructure lag; it’s a combination of cultural, economic, and historical factors that have made physical cash feel like the only trustworthy form of transaction for millions of consumers.
- Limited credit card penetration: Many consumers across CEE have never successfully completed a digital payment transaction, making unfamiliarity – not distrust – the primary barrier to adoption.
- Uneven banking infrastructure: Inconsistent access to modern banking services has reinforced cash-based purchasing habits, particularly outside major urban centres.
- Historical skepticism: Genuine concerns about online payment security, rooted in real or perceived negative experiences, have made physical cash feel like the only trustworthy transaction method for millions of consumers.
- Cultural and economic factors: Beyond infrastructure, deeply embedded commercial habits and historical economic instability have shaped a regional preference for cash that technology alone cannot quickly resolve.
What’s changing now is the pace of the underlying conditions. Smartphone penetration is rising sharply across CEE market dynamics, banking infrastructure is modernizing, and a younger generation of consumers is entering the market with fundamentally different payment expectations. Businesses that recognize this shift early and build systematic strategies to migrate customers toward digital alternatives will gain significant competitive and operational advantages. Those that continue treating cash on delivery as an unavoidable cost of doing business in the region will find themselves increasingly disadvantaged as digital-first competitors optimize their operations around lower-cost payment rails.
The payment transformation underway across Central and Eastern Europe isn’t a distant trend – it’s happening now, at different speeds in different markets. Your job as an eCommerce operator is to understand where your specific customer base sits on that adoption curve and build a migration strategy that moves them forward without losing them in the process. The businesses that get this right in the next 12 to 24 months will establish operational and cost structures that are genuinely difficult for slower-moving competitors to replicate, aligning with successful global eCommerce strategies. This foundation sets the stage for understanding exactly what COD is costing you today.
The Hidden Costs of Maintaining Cash on Delivery Operations
Here’s the uncomfortable truth about cash on delivery: most businesses dramatically underestimate what it actually costs them. On the surface, COD looks like a zero-fee payment method – no processing charges, no gateway fees, no interchange costs. But when you do a complete accounting of the operational costs, the picture changes entirely. The true cost of COD operations frequently reaches 3 to 5 percent of transaction value once you factor in the full operational burden, which is often higher than the transparent fees associated with digital payment alternatives.
The true cost components of COD operations
- Driver training and cash handling protocols: Every delivery driver who handles cash needs training on secure collection procedures, documentation requirements, and bank deposit processes – plus ongoing supervision to maintain compliance.
- Transport security measures: Logistics partners must implement security protocols across their entire delivery networks, creating meaningful overhead before a single transaction is processed.
- Reconciliation burden: Manual matching of delivery confirmations against cash receipts consumes several hours of accounts receivable team capacity every week, with documentation gaps generating error correction cycles that compound during month-end closing periods.
- Security liability: Cash storage requirements, theft liability insurance, and driver accountability systems create ongoing expenses that scale directly with transaction volume.
- Dispute resolution complexity: Missing documentation complicates dispute resolution, and manual reconciliation workflows create vulnerability to both unintentional errors and deliberate fraud.
- Opportunity cost: Finance teams that could be focused on strategic analysis are instead chasing paper trails and resolving discrepancies that automated digital payment systems would never create.
Start with the most obvious layer: driver training and cash handling protocols. Every delivery driver who handles cash needs training on secure collection procedures, documentation requirements, and bank deposit processes. This is a key consideration for eCommerce logistics in CEE. That training isn’t free, and it requires ongoing supervision to maintain compliance. Add the cost of transport security measures that logistics partners must implement across their entire delivery networks, and you’re already looking at meaningful overhead before a single transaction is processed.
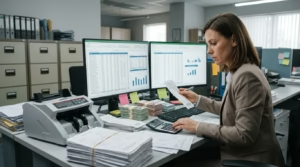
Then there’s the reconciliation burden. Manual matching of delivery confirmations against cash receipts consumes several hours of accounts receivable team capacity every week. Documentation gaps between handwritten receipts and digital accounting systems generate error correction cycles that compound processing delays, particularly during month-end closing periods. Finance teams that could be focused on strategic analysis are instead chasing paper trails and resolving discrepancies that automated digital payment systems would never create in the first place.
Security liability is another cost dimension that organizations rarely quantify accurately. Cash storage requirements, theft liability insurance, and driver accountability systems create ongoing expenses that scale directly with transaction volume. Missing documentation complicates dispute resolution, and manual reconciliation workflows create vulnerability to both unintentional errors and deliberate fraud. When you add up driver training, security protocols, reconciliation labor, bank deposit fees, and error correction overhead, the 3 to 5 percent cost estimate becomes not just plausible but conservative for high-volume operations.
The strategic case for payment processing modernization isn’t just about eliminating these costs — it’s about redirecting that operational capacity toward activities that actually grow your business. Every hour your finance team spends reconciling cash receipts is an hour not spent on customer analytics, pricing strategy, or growth planning. That opportunity cost compounds over time in ways that are harder to measure but equally real. For businesses processing significant order volumes, even a partial reduction in COD share can free up tens of thousands of dollars in annual operational costs that can be redeployed toward revenue-generating activities. Understanding these costs makes the case for digital alternatives much clearer.
Online Payment Solutions as Alternatives to Cash on Delivery
The range of viable digital payment methods for CEE eCommerce has expanded dramatically over the past several years. You’re no longer choosing between cash and a single card payment option – you have a sophisticated toolkit of online payment solutions that can be matched to different customer segments, transaction types, and operational requirements.
Most effective online payment solutions for replacing COD in CEE
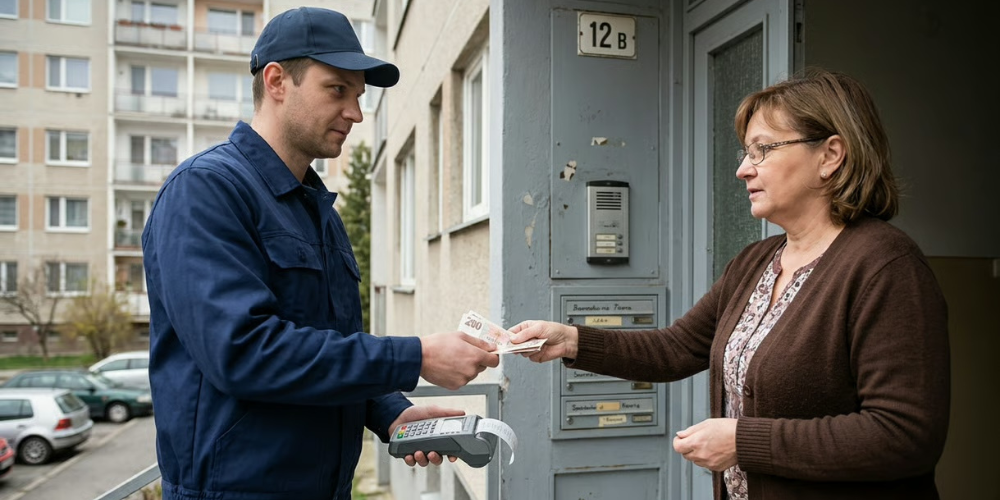
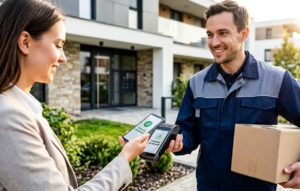
- Mobile payment terminals: Equipping delivery drivers with card readers or smartphone-based payment applications preserves the delivery-point transaction timing customers expect while eliminating physical currency exchange. Drivers become digital transaction facilitators, and payment confirmations synchronize automatically with enterprise systems without manual data entry.
- Payment portals: Self-service portals allow customers to select their preferred payment instrument during the ordering process, streamlining logistics coordination and reducing collection friction at the delivery point. When integrated with order management systems, portals can automatically flag pre-paid orders for expedited processing, creating a tangible service benefit that reinforces the value of digital payment.
- Real-time payment networks: Equivalents to systems like FedNow and RTP are emerging across CEE, enabling businesses to receive confirmed funds within seconds of digital payment initiation – directly matching the payment certainty that COD has historically offered at the moment of delivery.
- Automated audit trails: Every electronic transaction generates a comprehensive record that synchronizes directly with accounting systems, providing real-time visibility into collection performance and eliminating the documentation gaps that complicate dispute resolution under COD operations.
Mobile payment terminals are among the most effective bridging solutions for businesses in the early stages of COD reduction. By equipping delivery drivers with card readers or smartphone-based payment applications, you preserve the delivery-point transaction timing that customers expect while eliminating physical currency exchange. Drivers become digital transaction facilitators rather than cash handlers, and payment confirmations synchronize automatically with your enterprise systems without manual data entry. This approach is particularly powerful because it doesn’t require customers to change their behavior significantly – they still pay at the door, just digitally instead of with cash.
Payment portals offer a complementary approach for customers who are comfortable completing transactions before delivery. Self-service portals allow customers to select their preferred payment instrument during the ordering process, streamlining logistics coordination and reducing collection friction at the delivery point. When integrated with your order management system, these portals can automatically flag pre-paid orders for expedited processing, creating a tangible service benefit that reinforces the value of digital payment. Customers who experience faster fulfillment on pre-paid orders quickly internalize the connection between digital payment and better service.
Real-time payment networks represent a particularly compelling development for CEE markets. Equivalents to systems like FedNow and RTP are emerging across the region, enabling businesses to receive confirmed funds within seconds of digital payment initiation. This immediacy directly addresses one of the core operational advantages that cash on delivery has historically offered – the certainty of payment at the moment of delivery. When digital alternatives can match that immediacy while eliminating physical currency management, the operational case for COD becomes very difficult to sustain.
One of the most underappreciated advantages of digital payment methods is the audit trail they create automatically. Every electronic transaction generates a comprehensive record that synchronizes directly with your accounting systems, providing real-time visibility into collection performance and eliminating the documentation gaps that complicate dispute resolution under COD operations. For businesses operating across multiple CEE markets with varying regulatory requirements, this automated compliance documentation is genuinely valuable beyond its operational convenience. It also dramatically simplifies VAT reporting and cross-border financial reconciliation, which are persistent pain points for regional operators managing multi-country footprints. These solutions work best when paired with strategic adoption programs that address customer concerns directly.
Digital Wallet Adoption Strategies for CEE Markets
Digital wallets occupy a unique strategic position in your COD phase-out toolkit because they combine the immediacy of delivery-point payment with the operational efficiency of digital processing. This is particularly relevant given the evolving Balkan digital payment adoption trends. When a customer pays through a mobile payment solutions application at the door, you get the same real-time payment confirmation you’d get from cash – but without the security protocols, reconciliation labor, or bank deposit runs that cash requires. The challenge is getting customers to that first successful digital wallet adoption transaction, because that experience is typically what converts skeptics into advocates.
How to drive digital wallet adoption among COD-reliant customers
- Build infrastructure first by deploying mobile payment applications designed for CEE market conditions, with offline transaction capabilities and low-bandwidth synchronization protocols that ensure reliable payment collection regardless of network conditions.
- Invest in customer education that demonstrates immediate, tangible value – faster transaction processing, enhanced security features, and the elimination of the need to have exact change ready are concrete benefits that resonate with first-time digital payment users.
- Launch pilot programs targeting your most collaborative customer segments – those with strong payment histories and positive service relationships – to create adoption momentum and generate peer recommendations.
- Introduce incentive structures framed around convenience rather than discounts, such as modest convenience fees on high-cost payment methods alongside zero-fee alternatives through digital channels, allowing customers to make an economically rational choice without feeling pressured.
- Monitor the first 90 days of each customer’s digital payment experience with dedicated support resources, as early positive experiences are the primary driver of lasting behavioral change.
The most effective adoption strategies start with infrastructure, not incentives. Mobile payment solutions designed for CEE market conditions need to address regional infrastructure limitations directly, particularly the inconsistent internet connectivity that characterizes many delivery routes outside major urban centers. Applications with offline transaction capabilities and low-bandwidth synchronization protocols ensure that payment collection continues reliably regardless of network conditions – a prerequisite for driver confidence and operational consistency. If your drivers experience failed transactions due to connectivity issues, they’ll revert to cash, and so will your customers.
Customer education is where most businesses underinvest. Rather than simply announcing that digital wallets are now available, the most successful operators demonstrate immediate, tangible value. Faster transaction processing, enhanced security features, and the elimination of the need to have exact change ready are all concrete benefits that resonate with customers who’ve never had a reason to try digital payment before. Pilot programs targeting your most collaborative customer segments – those with strong payment histories and positive service relationships – create adoption momentum and generate the peer recommendations that are far more persuasive than any marketing message you can craft.
Incentive structures play an important supporting role, but they work best when framed around convenience rather than discounts. Introducing modest convenience fees on high-cost payment methods while offering zero-fee alternatives through digital channels allows customers to make an economically rational choice without feeling pressured. This approach steers behavior toward lower-cost payment rails while maintaining customer autonomy, which is critical in markets where trust is still being established. The goal is to make digital wallets the obviously better choice, not the only choice. Businesses that frame digital payment as a customer benefit rather than a business requirement consistently achieve higher digital wallet adoption rates and lower churn during the transition period. With the right wallet strategy in place, you’re ready to implement a structured phase-out program.
COD Reduction Methods: Phased Transition Approaches
The single biggest mistake businesses make when attempting to reduce COD dependency is moving too fast. Abrupt payment method changes create customer resistance, damage relationships, and can trigger order cancellations that offset any operational savings you achieve. The businesses that execute this transition most successfully treat it as a 6 to 12 month program, not a policy change, and they build their approach around customer migration strategies rather than blanket mandates.
How to systematically reduce COD dependency without losing customers
- Identify your most collaborative customer segments – accounts with strong payment histories, solid financial profiles, and demonstrated openness to operational improvements – and begin digital payment migration with these early adopters first.
- Implement parallel processing periods during which both cash and digital payment options remain available, eliminating forced conversion pressure and allowing customers to migrate toward digital options naturally as they experience the convenience benefits firsthand.
- Establish transaction volume thresholds that require digital payment for high-value orders while maintaining COD availability for smaller transactions, targeting the orders that consume disproportionate reconciliation resources.
- Deploy dedicated support resources during the first 90 days of each customer’s digital payment experience to address concerns proactively and improve long-term retention.
- Track adoption velocity, customer feedback patterns, and operational cost reductions on a weekly basis, and adjust timelines based on actual performance rather than arbitrary deadlines.
Start by identifying your most collaborative customer segments – accounts with strong payment histories, solid financial profiles, and demonstrated openness to operational improvements. These customers are your early adopters, and working with them first serves two purposes: it allows your team to refine processes and troubleshoot issues with receptive partners before you face resistant ones, and it creates a cohort of advocates who can speak credibly to the benefits of digital payment from their own experience. This segmentation approach is consistently more effective than attempting universal migration across your entire customer base simultaneously.
Parallel processing periods are non-negotiable components of any effective phased transition. During the transition window, both cash and digital payment options remain available, which eliminates the forced conversion pressure that generates the most customer resistance. Most customers, when given a genuine choice and adequate support, will migrate toward digital options naturally once they experience the convenience benefits firsthand. Your role during this period is to make the digital path as frictionless as possible while monitoring adoption rates and addressing concerns proactively. Dedicated support resources during the first 90 days of a customer’s digital payment experience make a measurable difference in long-term retention.
Transaction volume thresholds create natural migration triggers that reduce operational burden without requiring explicit policy changes. Establishing minimum order values that require digital payment – while maintaining COD availability for smaller transactions – targets the high-value orders that consume disproportionate reconciliation resources. This tiered approach is particularly effective because it’s easy for customers to understand and accept: the logic of “larger orders require more secure payment methods” is intuitive and rarely generates significant pushback. It also concentrates your operational savings where they matter most, since high-value orders carry the highest absolute COD processing costs.
Throughout the transition, your monitoring systems are as important as your migration tactics. Tracking adoption velocity, customer feedback patterns, and operational cost reductions on a weekly basis gives you the data you need to adjust timelines based on actual performance rather than arbitrary deadlines. Companies that implement systematic measurement frameworks identify process bottlenecks early and make targeted interventions that accelerate digital adoption without compromising customer satisfaction during the critical transition window. But even the best-designed transition program won’t succeed without addressing the trust issues that drive COD preference in the first place.
Building Customer Trust to Overcome COD Dependency
If you want to understand why COD persists so stubbornly in CEE markets despite the operational costs it imposes on everyone involved, you need to understand what it actually represents to the customer. Cash on delivery isn’t just a payment method – it’s a risk management strategy. It’s how consumers who don’t fully trust online commerce protect themselves from receiving the wrong product, a damaged item, or nothing at all. Until you address that underlying concern, no amount of digital payment infrastructure will move the needle on adoption.
Trust-building measures that address the underlying reasons customers prefer COD
- Specific, verifiable security commitments: Clear refund guarantees, straightforward dispute resolution procedures, and regulatory compliance certifications that customers can independently verify are more persuasive than abstract security promises or technical explanations of encryption standards.
- Pilot programs with early adopters: When customers in your target market see peers successfully completing digital transactions and receiving the service quality they expected, the psychological barrier to trying it themselves drops significantly.
- Peer advocacy: Finance teams that invest in gradual trust-building strategies consistently find that early adopters become advocates who influence broader customer populations through peer recommendations – and that organic trust expansion is far more durable than adoption driven by incentives alone.
- Tangible first-experience benefits: The transaction completes faster, there’s no need to have exact change ready, and the electronic receipt provides a clearer record than a handwritten delivery note – concrete advantages that transform abstract concerns into concrete confidence after a single successful digital payment.
Transparent communication about payment security protocols is the foundation, but it’s not sufficient on its own. Explaining encryption standards and fraud protection measures in accessible language helps, but abstract security promises don’t overcome concrete distrust built from real or perceived negative experiences. What actually works is demonstrating reliability through tangible, verifiable commitments: clear refund guarantees, straightforward dispute resolution procedures, and regulatory compliance certifications that customers can independently verify. The more specific and concrete your security commitments, the more credible they become. Vague assurances that “your payment is secure” carry almost no persuasive weight with consumers who’ve been skeptical of digital commerce for years.
Pilot programs with early adopters create the social proof that technical explanations cannot. When customers in your target market see peers successfully completing digital transactions and receiving the service quality they expected, the psychological barrier to trying it themselves drops significantly. Finance teams that invest in gradual trust-building strategies consistently find that early adopters become advocates who influence broader customer populations through peer recommendations – and that organic trust expansion is far more durable than adoption driven by incentives alone.
The practical reality is that COD dependency diminishes naturally once customers have a positive first experience with digital payment. The transaction completes faster, there’s no need to have exact change ready, and the electronic receipt provides a clearer record than a handwritten delivery note. That first successful experience transforms abstract concerns into concrete confidence, and concrete confidence is what drives lasting behavioral change across CEE markets. Building the conditions for that first positive experience – through education, support, and reliable technology – is the most important investment you can make in your COD phase-out program. Trust-building efforts need to be supported by robust technical infrastructure that makes digital payment genuinely reliable.
Technology Infrastructure for Payment Processing Modernization
Effective payment processing modernization isn’t just about adding a card reader to your delivery fleet – it requires foundational technology infrastructure that connects delivery operations, financial systems, and customer interfaces through automated data exchange. Without that integration backbone, you end up with digital payment collection that still requires manual reconciliation, which captures only a fraction of the operational benefits you’re trying to achieve.
Essential technical capabilities for COD phase-out
- ERP integration: When payment capture at delivery points synchronizes instantly with the general ledger, manual data entry cycles that traditionally extend cash application timelines by two to four days are eliminated – directly improving the cash conversion cycle.
- Mobile payment terminals with offline capability: Modern terminals process payments instantly while capturing electronic signatures and delivery confirmations simultaneously. Low-bandwidth connectivity support and local transaction storage for offline processing are requirements, not optional features, for CEE infrastructure conditions.
- AI-powered payment recognition: Automation systems that automatically correlate incoming payments with delivery orders – even when customer reference data is incomplete or inconsistent – reduce reconciliation labor from hours to minutes while improving accuracy beyond manual verification.
- Unified reporting dashboards: Consolidated visibility into COD transactions alongside digital payments enables comparative cost analysis, payment method steering decisions, and customer migration prioritization across payment methods, customer segments, and geographic regions.
Enterprise resource planning integration is the critical starting point. When payment capture at delivery points synchronizes instantly with your general ledger accounts, you eliminate the manual data entry cycles that traditionally extend cash application timelines by two to four days beyond actual delivery completion. That timeline compression has direct working capital implications – funds that were previously tied up in reconciliation queues become available immediately, improving your cash conversion cycle in ways that CFOs can quantify precisely. For businesses with significant order volumes, this improvement alone can justify the technology investment within the first year of implementation.
Mobile payment terminals equipped with card readers and digital wallet compatibility are the operational interface between your drivers and your financial systems. Modern terminals process payments instantly while capturing electronic signatures and delivery confirmations simultaneously, creating comprehensive transaction records that eliminate the documentation gaps that plague traditional COD reconciliation. Critically, these devices need to operate effectively under CEE infrastructure conditions, which means low-bandwidth connectivity support and local transaction storage for offline processing are requirements, not nice-to-have features.
AI-powered payment recognition technology addresses the reconciliation challenge at scale. These automation systems automatically correlate incoming payments with delivery orders even when customer reference data is incomplete or inconsistent – a common occurrence in markets where manual ordering processes are still prevalent. Reducing reconciliation labor from hours to minutes while improving accuracy beyond what manual verification achieves is a measurable, quantifiable improvement that justifies the technology investment on its own.
The reporting layer matters as much as the transaction processing layer. Unified dashboards that consolidate COD transactions alongside digital payments give you the comparative cost analysis you need to make informed decisions about payment method steering and customer migration priorities. Real-time visibility into collection performance across payment methods, customer segments, and geographic regions transforms payment digitization from an operational project into a strategic intelligence capability – one that informs pricing decisions, customer segmentation strategies, and market expansion planning in ways that cash-based operations simply cannot support. This infrastructure becomes particularly valuable as contactless payment adoption accelerates across the region.
Contactless Payment Growth and Its Role in COD Replacement
Contactless payment growth has developed faster across Central and Eastern Europe than most market observers predicted five years ago, and that acceleration creates a genuine opportunity for businesses looking to replace COD with something customers will actually use. Near-field communication technology enables customers to complete payments through a card tap or smartphone proximity in seconds, without PIN entry or signature verification for amounts below regional threshold limits. That simplicity is important – it means the digital alternative is actually faster and less friction-filled than handling cash, which is a compelling argument for customers who’ve been skeptical of digital payment complexity.
How contactless payment growth accelerates COD phase-out in CEE
- Faster delivery-point transactions: Drivers equipped with contactless-enabled terminals no longer handle physical currency or coordinate bank deposit runs, reducing security protocols, eliminating cash handling liability, and accelerating the cash application timeline from days to minutes.
- Seamless system integration: Payment data captures automatically and synchronizes with enterprise accounting systems in real time, turning a multi-step manual process into a seamless automated workflow.
- Reduced behavioral change required: The transaction still happens at the delivery point, still provides immediate confirmation, and still feels like a direct exchange – just without the physical currency, lowering the perceived barrier to adoption.
- Operational reliability across geographies: Low-bandwidth synchronization capabilities and offline transaction storage ensure payment processing continuity in areas with inconsistent internet connectivity, making contactless viable for rural and semi-urban markets across the region.
- Driver satisfaction improvement: Eliminating cash handling responsibility reduces stress and accountability burden in ways that contribute to lower turnover in delivery roles.
The operational impact on your delivery operations is significant. Drivers equipped with contactless-enabled terminals no longer handle physical currency or coordinate bank deposit runs, which reduces security protocols, eliminates cash handling liability, and accelerates the cash application timeline from days to minutes. Payment data captures automatically and synchronizes with your enterprise accounting systems in real time, turning what was a multi-step manual process into a seamless automated workflow. Driver satisfaction also improves measurably – eliminating cash handling responsibility reduces stress and accountability burden in ways that contribute to lower turnover in delivery roles.
From the customer’s perspective, contactless payment addresses the specific concerns that historically drove COD preferences without requiring them to navigate complex digital interfaces or share sensitive payment credentials in advance. The transaction still happens at the delivery point, still provides immediate confirmation, and still feels like a direct exchange – just without the physical currency. That continuity of experience is strategically important because it reduces the perceived behavioral change required, which is one of the primary barriers to digital payment adoption in CEE markets.
The scalability of contactless infrastructure across diverse geographic conditions is another practical advantage. Low-bandwidth synchronization capabilities and offline transaction storage ensure payment processing continuity in areas with inconsistent internet connectivity, which is a real operational consideration for businesses serving rural and semi-urban markets across the region. As contactless terminal costs continue to decline and regional banking infrastructure expands, the economic case for equipping your entire delivery fleet with contactless capability becomes increasingly straightforward. However, the effectiveness of contactless payment varies significantly across different CEE countries, requiring market-specific implementation strategies.
Country-Specific Considerations Across CEE Markets
One of the most common strategic mistakes in CEE payment transformation is treating the region as a single market. The variation in COD prevalence, digital payment adoption, and consumer trust levels across individual countries is substantial enough that a strategy optimized for Poland will underperform significantly in Romania, and vice versa. This highlights the importance of a tailored CEE eCommerce localization strategy. Building country-specific approaches within a regional framework isn’t optional – it’s the difference between a successful transition and a costly one.
| Market | Digital Adoption Level | Key Characteristics | Recommended Approach |
|---|---|---|---|
| Poland | High | Smartphone penetration exceeding 75 percent; mature digital banking ecosystem | Accelerated migration timeline; digital wallets and contactless payments viable at scale |
| Romania | Low | Strong cash preferences rooted in historical banking instability; limited credit card ownership | Patient trust-building strategies; longer parallel processing periods before digital alternatives gain traction |
| Bulgaria | Mixed | Urban market digitalization coexists with rural logistics challenges; economic development disparities influence payment preferences | Differentiated urban/rural strategies; technology alone cannot quickly resolve infrastructure gaps |
| Hungary | Moderate | Digital payment adoption meaningfully accelerated by government initiatives promoting electronic transactions | Leverage regulatory tailwinds; policy environment shapes adoption as much as consumer preferences |
| Estonia / Baltic states | Very High | Most advanced digital payment markets in CEE; infrastructure and consumer behaviour closer to Western Europe | Rapid phase-out feasible; apply Western European migration playbooks with regional adjustments |
Poland and Romania represent opposite ends of the digital adoption spectrum within the region. Polish consumers increasingly embrace digital wallets and contactless payments, driven by smartphone penetration rates exceeding 75 percent and a relatively mature digital banking ecosystem. Romanian consumers, by contrast, maintain strong cash preferences rooted in historical banking instability and limited credit card ownership, requiring more patient trust-building strategies and longer parallel processing periods before digital alternatives gain meaningful traction. Attempting to apply Poland’s accelerated migration timeline to Romanian operations is a reliable way to generate customer attrition without achieving proportional operational savings.
Bulgaria presents a particularly complex picture, where urban market digitalization coexists with rural logistics challenges that perpetuate cash on delivery dependency. The infrastructure gaps between Sofia and rural regions aren’t just connectivity issues – they reflect broader economic development disparities that influence consumer payment preferences in ways that technology alone cannot quickly resolve. Hungary demonstrates moderate digital payment adoption that has been meaningfully accelerated by government initiatives promoting electronic transactions, which is a reminder that regulatory and policy environments shape adoption trajectories as much as consumer preferences do.
The Baltic states – Estonia in particular – represent the most advanced digital payment markets in the CEE region, with infrastructure and consumer behavior that more closely resembles Western Europe than the Balkans. Businesses operating across the full CEE footprint need to account for these divergent trajectories in their technology selection, operational procedures, and customer communication strategies. Regulatory frameworks governing electronic payments also differ substantially across CEE jurisdictions, creating compliance complexity that requires localized legal review before implementing digital payment infrastructure in each new market. These country-specific variations make systematic performance measurement essential for optimizing your regional strategy.
Measuring Success in Cash on Delivery Reduction Initiatives
You can’t manage what you don’t measure, and COD phase-out is no exception. The businesses that execute this transition most effectively are those that establish clear performance metrics before the program begins, track them consistently throughout, and use the data to make real-time adjustments rather than waiting for quarterly reviews to identify problems.
KPIs to track during COD phase-out
- Digital payment adoption rate: The percentage of orders processed through digital channels versus cash on delivery, tracked weekly to establish baseline and reveal adoption velocity trends that require strategic response. Stagnation is an early warning signal that incentive design, customer education, or technical friction needs adjustment.
- Days sales outstanding by payment method: Automated digital payments typically reduce the timeline from delivery completion to funds availability from three to four days down to same-day or next-day settlement – a compression that translates directly to working capital improvements CFOs can express in precise monetary terms.
- Operational cost per transaction: Comprehensive cost accounting capturing driver training, cash handling security protocols, bank deposit fees, and reconciliation labor hours – typically totaling 3 to 5 percent of transaction value for COD – compared against transparent digital payment processing fees provides the clearest picture of actual savings achieved.
- Customer satisfaction scores among recently migrated accounts: Tracking satisfaction during and after the transition window identifies relationship strain early and validates that operational savings are not being offset by customer attrition.
Transaction volume by payment method is your most fundamental tracking metric. Monitoring the percentage of orders processed through digital channels versus cash on delivery on a weekly basis establishes your baseline and reveals adoption velocity trends that require strategic response. Stagnation in digital adoption rates is an early warning signal that something in your migration approach needs adjustment – whether that’s incentive design, customer education, or technical friction in the payment experience itself.
Days sales outstanding analysis segmented by payment method is where the financial impact becomes concrete. Finance teams that calculate average time from delivery completion to funds availability typically discover that automated digital payments reduce this timeline from three to four days down to same-day or next-day settlement. That compression translates directly to working capital improvements that CFOs can express in precise monetary terms, which is the language that secures continued investment in the transformation program.
Operational cost per transaction is the most revealing metric for evaluating overall program effectiveness. Comprehensive cost accounting that captures driver training expenses, cash handling security protocols, bank deposit fees, and reconciliation labor hours – typically totaling 3 to 5 percent of transaction value for COD – compared against transparent digital payment processing fees provides the clearest possible picture of actual savings achieved. That comparison is your most powerful tool for justifying continued investment and demonstrating ROI to stakeholders who need to see measurable outcomes. Tracking this metric monthly against your pre-program baseline creates the evidence base that sustains organizational commitment through the full 6 to 12 month transition period. These metrics become even more valuable as you look ahead to the broader payment transformation underway across the region.
Future Outlook: Payment Transformation in CEE Markets
The trajectory of payment transformation across Central and Eastern Europe points clearly toward accelerating COD decline, driven by converging forces that are largely outside any individual business’s control. Smartphone penetration exceeding 75 percent in markets like Poland creates the infrastructure foundation for widespread digital wallet adoption, while younger consumers entering the market demonstrate payment preferences that are fundamentally different from the generations that established cash-on-delivery as the regional norm. This demographic transition reduces COD dependency organically over time, but businesses that actively accelerate the shift will capture competitive advantages that passive operators will not.
Emerging payment technologies accelerating COD decline in CEE
- Real-time payment networks: As instant payment rails become more widely available across CEE, the immediacy advantage that cash on delivery has historically offered – confirmed payment at the moment of delivery – becomes replicable through digital channels, removing the most durable operational argument for cash-based delivery payment.
- Blockchain verification systems: Immutable transaction records provide payment assurance that manual cash processes cannot replicate, making the security benefits of digital payment tangible and verifiable rather than abstract.
- Advanced fraud detection technologies: Automated reconciliation capabilities and AI-driven fraud prevention address the trust concerns that have historically been the most durable barrier to digital payment adoption in the region.
- Demographic shift: Younger consumers entering CEE markets demonstrate payment preferences fundamentally different from the generations that established COD as the regional norm, reducing dependency organically over time regardless of active migration programs.
Real-time payment networks emerging throughout CEE markets are perhaps the most significant structural development for COD replacement. As instant payment rails become more widely available, the immediacy advantage that cash on delivery has historically offered – confirmed payment at the moment of delivery – becomes replicable through digital channels. When digital alternatives can match COD’s immediacy while eliminating its operational overhead, the remaining arguments for maintaining cash-based delivery payment become very difficult to sustain.
Blockchain verification systems and advanced fraud detection technologies are addressing the trust concerns that have historically been the most durable barrier to digital payment adoption in the region. Immutable transaction records and automated reconciliation capabilities provide payment assurance that manual cash processes cannot replicate, while making the security benefits of digital payment tangible and verifiable rather than abstract. The businesses that invest in these capabilities now will be positioned to capture the full operational and competitive benefits of a digitally transformed payment landscape as CEE markets continue their evolution toward electronic commerce maturity. The window for building that competitive position is open today – but it won’t stay open indefinitely as the market converges on digital payment as the regional standard.
Frequently Asked Questions
- What is the most effective first step for reducing COD dependency in a CEE eCommerce operation? Start with customer segmentation rather than a blanket policy change. Identify your most collaborative accounts – those with strong payment histories and positive service relationships – and pilot digital payment options with them first. This approach lets you refine your processes with receptive customers before addressing more resistant segments, and it generates the peer advocacy that drives broader adoption more effectively than any marketing campaign.
- How long should a COD phase-out transition program realistically take? Most successful implementations span 6 to 12 months. Shorter timelines create customer resistance and relationship strain, while longer programs lose momentum and fail to capture operational savings quickly enough to justify the investment. The right timeline for your business depends on your customer mix, the digital payment infrastructure available in your specific markets, and the resources you can dedicate to customer education and support.
- What digital payment alternatives work best for customers who still want to pay at delivery? Mobile payment terminals equipped with contactless readers are the most effective bridging solution. They preserve the delivery-point transaction timing customers expect while eliminating physical currency exchange. Customers can tap a card or smartphone to complete payment in seconds, which is actually faster than handling cash and requires no behavioral change beyond the payment instrument itself.
- How do you calculate the true cost of COD operations to build the business case for change? Comprehensive cost accounting should capture driver training expenses, cash handling security protocols, bank deposit fees, reconciliation labor hours, theft liability insurance, and error correction overhead. When all these factors are included, total COD processing costs typically range from 3 to 5 percent of transaction value – often higher than the transparent fees associated with digital payment alternatives.
- Which CEE markets are most ready for rapid COD phase-out, and which require more patience? Poland and the Baltic states, particularly Estonia, are most ready for accelerated digital migration due to high smartphone penetration and mature digital banking infrastructure. Romania and Bulgaria require more patient approaches, with longer parallel processing periods and more intensive trust-building investment. Hungary sits in the middle, with government-supported digital payment initiatives accelerating adoption beyond what consumer preferences alone would drive.
- What incentive structures are most effective for steering customers toward digital payment? Convenience fees on high-cost payment methods combined with zero-fee alternatives through digital channels consistently outperform discount-based incentives. This approach frames the choice as economically rational rather than coercive, maintains customer autonomy, and creates lasting behavioral change rather than temporary adoption driven by one-time promotions. The goal is to make digital payment the obviously better choice, not the only choice.
- What technology integrations are essential for a successful COD phase-out program? ERP integration for real-time payment synchronization, mobile payment terminals with offline transaction capability, and AI-powered reconciliation automation are the three most critical components. Without ERP integration, you capture digital payments but still require manual reconciliation. Without offline capability, your drivers revert to cash in areas with poor connectivity. Without automated reconciliation, you reduce cash handling but don’t eliminate the labor overhead that drives much of COD’s true cost.
- How do you address customer trust concerns about online payment security in CEE markets? Lead with specific, verifiable commitments rather than abstract security assurances. Clear refund guarantees, straightforward dispute resolution procedures, and independently verifiable regulatory compliance certifications are more persuasive than technical explanations of encryption standards. Pilot programs with early adopters who can speak credibly to their positive experiences are more effective than any marketing message you can craft about security features.
- What KPIs should be tracked weekly during a COD phase-out program? Track digital payment adoption rate as a percentage of total orders, days sales outstanding segmented by payment method, operational cost per transaction by payment type, and customer satisfaction scores among recently migrated accounts. Weekly tracking of adoption velocity reveals stagnation patterns early enough to make tactical adjustments before they become strategic problems.
- How will emerging payment technologies further accelerate COD decline in CEE over the next few years?Real-time payment networks that match COD’s immediacy while eliminating physical currency management will remove the most durable operational argument for cash-based delivery payment. Combined with rising smartphone penetration, generational shifts in payment preferences, and blockchain-based verification systems that address trust concerns at scale, these developments will make COD increasingly difficult to justify operationally or competitively. Businesses that build digital payment infrastructure now will be positioned to capture the full benefits of this transition as it accelerates.
References
- Logicos 3PL – True Cost of Cash on Delivery for eCommerce Merchants. COD logistics carrier commissions typically 1–5% of transaction value; total operational cost (including RTO, reconciliation, security) often reaches 3–7%+.
- Mordor Intelligence – Romania eCommerce Market Report 2024. COD accounts for 50–65% of online transactions in Romania.
- The Paypers – Payments and Commerce Market Guide CEE. COD share in Bulgaria approximately 55–60% of eCommerce orders.
- DataReportal – Digital 2024 Poland. Internet penetration 88.1%, mobile connections at 130.8% of population; strong proxy for high smartphone adoption exceeding 75%.
- eCommerce Europe – European eCommerce Report 2025. Regional payment landscape dynamics and digital adoption trends across CEE.
- PayU – CEE Payment Insights. Regional payment method adoption, digital wallet growth, and COD migration strategies.